Key Takeaways
- Original Medicare includes Part A for hospital insurance and Part B for medical insurance, but prescription drug coverage generally requires a separate Part D plan.
- Medicare Advantage plans that include prescription drug coverage can combine hospital, medical, and drug benefits into one plan.
- Original Medicare can be paired with a stand-alone Part D plan and, if desired, a Medicare Supplement Insurance (Medigap) policy to help manage out-of-pocket costs.
- The right Medicare coverage depends on your healthcare needs, prescription medications, preferred doctors, budget, and lifestyle.
- Comparing total costs and coverage details before enrolling can help you make a more informed decision.
Understanding Your Medicare Coverage Options
Choosing Medicare coverage can feel overwhelming, especially when you are trying to understand how hospital stays, doctor visits, and prescription medications fit together.
The good news is that Medicare offers different ways to arrange your coverage. Some options combine several types of benefits into one plan, while others allow you to choose separate coverage for medical services, prescriptions, and certain out-of-pocket expenses.
At Life and Med, our goal is to make Medicare easier to understand so you can explore your options with confidence.
The Different Parts of Medicare Explained
Medicare is divided into four main parts, each serving a different purpose.
Medicare Part A: Hospital Insurance
Part A helps cover eligible inpatient hospital care, skilled nursing facility care under qualifying conditions, hospice care, and certain home health services.
Although Part A is often called hospital insurance, it does not mean every hospital-related service is covered in every circumstance. Deductibles, coinsurance, eligibility requirements, and coverage rules may apply.
Medicare Part B: Medical Insurance
Part B helps cover medically necessary outpatient care and preventive services. Examples include:
- Doctor appointments and specialist visits.
- Outpatient procedures and medical services.
- Laboratory tests and diagnostic screenings.
- Preventive screenings and certain vaccinations.
- Durable medical equipment and other eligible medical services.
Most people pay a monthly Part B premium and may also be responsible for deductibles and coinsurance.
Medicare Part C: Medicare Advantage
Medicare Advantage plans are offered by private insurance companies approved by Medicare. They provide the benefits covered by Original Medicare Parts A and B and may include additional benefits.
Many Medicare Advantage plans also include prescription drug coverage. These plans are often called Medicare Advantage Prescription Drug plans, or MA-PD plans.
Depending on the plan, additional benefits may include dental, vision, hearing, or other services. Coverage, costs, and availability vary.
Medicare Part D: Prescription Drug Coverage
Part D helps pay for eligible prescription medications. You can generally obtain this coverage through a stand-alone prescription drug plan paired with Original Medicare or through a Medicare Advantage plan that includes drug benefits.
Original Medicare does not automatically include outpatient prescription drug coverage, so it is important to understand your options when enrolling.
Option 1: Combine Hospital, Medical, and Drug Coverage With Medicare Advantage
If you want hospital care, doctor visits, and prescription drug coverage under one plan, a Medicare Advantage plan that includes Part D may be a convenient option.
These plans combine Medicare-covered hospital and medical services with prescription drug coverage, when included in the plan. You generally use one plan membership card for the benefits provided through that plan.
Depending on the plan, you may also receive additional benefits not typically covered by Original Medicare.
What to Consider Before Choosing Medicare Advantage
Medicare Advantage plans often use provider networks. Depending on the plan type, you may need to use network doctors and hospitals or pay more for certain out-of-network services.
Before enrolling, consider the following:
- Are your current doctors, specialists, and preferred hospitals included in the network?
- Does the plan cover your prescription medications?
- What are the monthly premium, deductible, copayments, and coinsurance?
- Does the plan require referrals or prior authorization for certain services?
- What is the plan’s annual out-of-pocket maximum for covered medical services?
- Are the additional benefits useful for your healthcare needs?
A plan with a low monthly premium may still involve substantial costs when you need medical care. Reviewing the complete cost structure can help you avoid surprises.
Option 2: Combine Original Medicare With Part D and Medigap
Another option is to keep Original Medicare and select additional coverage to meet your needs.
This approach generally involves:
- Medicare Part A: Hospital insurance.
- Medicare Part B: Medical insurance.
- Medicare Part D: A separate prescription drug plan.
- Medigap, if desired: A Medicare Supplement Insurance policy that helps cover certain out-of-pocket costs left by Original Medicare.
One benefit of Original Medicare is provider flexibility. You can generally visit any doctor or hospital nationwide that accepts Medicare and is accepting new Medicare patients, without being limited to a Medicare Advantage plan’s provider network.
A Medigap policy can help pay certain expenses, such as applicable coinsurance and deductibles, depending on the policy you choose. Popular options include Medigap Plan G and Plan N, which have different premiums and cost-sharing rules.
However, Medigap policies do not include outpatient prescription drug coverage. You would generally need a separate Part D plan for that coverage.
What to Consider With Original Medicare
Before choosing this combination, review:
- The monthly premiums for Part B, Part D, and any Medigap policy.
- Your potential deductibles, copayments, and coinsurance.
- Whether your preferred healthcare providers accept Medicare.
- The prescription medications covered by your Part D plan.
- Whether you qualify for guaranteed-issue protections or may need to undergo medical underwriting when applying for Medigap.
This approach may appeal to people who value provider flexibility and want supplemental coverage to help manage eligible out-of-pocket expenses. However, the overall cost depends on the policies selected and the healthcare services used.
Medicare Advantage vs. Original Medicare: How Do They Compare?
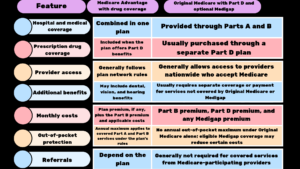
Important: Benefits, premiums, networks, and cost-sharing vary by plan and location. Review the specific plan documents before making a decision.
Understanding Medicare Costs
The cost of Medicare depends on the coverage you choose, your income, your healthcare needs, and the services you use.
When comparing options, look beyond the monthly premium.
Monthly Premiums
You may pay a premium for Medicare Part B, a stand-alone Part D plan, a Medigap policy, or a Medicare Advantage plan, depending on your selection.
Some Medicare Advantage plans advertise a $0 additional plan premium. This does not mean Medicare coverage is entirely free; you generally still need to account for your Part B premium and applicable out-of-pocket costs.
Deductibles, Copayments, and Coinsurance
A deductible is the amount you pay for covered services before your plan begins paying under the applicable rules. Copayments are fixed amounts you pay for certain services, while coinsurance is a percentage of the cost.
These amounts differ among Medicare options and may affect your overall healthcare spending.
Annual Out-of-Pocket Maximums
Medicare Advantage plans include an annual limit on what you pay for covered Part A and Part B services under the plan’s rules. Prescription drug costs are handled separately under applicable Part D cost-sharing rules.
Original Medicare does not have a general annual out-of-pocket maximum for Part A and Part B services. A Medigap policy may help cover certain eligible expenses, depending on the plan.
Income-Related Monthly Adjustment Amounts (IRMAA)
Some beneficiaries pay higher Medicare Part B and Part D premiums because of their income. These additional amounts are known as Income-Related Monthly Adjustment Amounts, or IRMAA.
If your income has decreased because of certain qualifying life events, you may be able to request that Social Security reconsider the income information used to determine your premium adjustment.
For current premiums, deductibles, and income-related adjustments, visit Medicare.gov or contact the Social Security Administration as appropriate.
Common Medicare Coverage Mistakes to Avoid
Taking time to understand your options can help you avoid costly or inconvenient mistakes.
1. Assuming Original Medicare Covers Prescriptions
Original Medicare generally does not cover most outpatient prescription drugs. Review Part D options or Medicare Advantage plans that include prescription coverage.
2. Choosing a Plan Based Only on Its Premium
A low premium does not necessarily mean the plan will cost less overall. Consider deductibles, copayments, coinsurance, prescription costs, and your expected healthcare needs.
3. Forgetting to Check Your Prescription Drug Coverage
Different plans may cover the same medication at different costs or apply different restrictions. Review each plan’s formulary and pharmacy requirements before enrolling.
4. Overlooking Provider Networks
If you choose Medicare Advantage, verify that your doctors and hospitals participate in the plan. Network rules can affect your access to care and your costs.
5. Missing Enrollment Deadlines
Medicare has specific enrollment periods. Delaying enrollment in certain coverage without qualifying circumstances may result in penalties or restrictions on when you can enroll.
If you are still working, have employer coverage, or are losing existing insurance, check whether special enrollment rules apply to your situation.
6. Assuming Medigap Includes Prescription Coverage
Medigap policies help cover certain costs associated with Original Medicare but do not provide outpatient prescription drug coverage. You will generally need a separate Part D plan if you want that coverage.
How to Choose the Right Medicare Coverage for You
There is no single Medicare option that works best for everyone. Your ideal coverage depends on your personal circumstances and preferences.
Start by asking yourself these questions:
- Which doctors, specialists, and hospitals do I want to continue using?
- Which prescription medications do I take regularly?
- How much can I comfortably spend on premiums and out-of-pocket expenses?
- Do I prefer a plan with a provider network or greater flexibility to choose Medicare-participating providers?
- Would additional benefits such as dental, vision, or hearing coverage be valuable to me?
- Am I eligible to enroll or make changes during the current enrollment period?
Once you understand your priorities, compare the plans available in your area. Medicare’s official Plan Finder at Medicare.gov can help you review plan benefits, estimated costs, provider information where available, and prescription drug coverage.
You can also consult a licensed Medicare professional if you need help understanding the differences between available options.
Frequently Asked Questions
Can one Medicare plan cover hospital care, doctor visits, and prescriptions?
Yes. A Medicare Advantage plan that includes prescription drug coverage can combine hospital, medical, and drug benefits in one plan. Original Medicare covers hospital and medical services, but prescription drug coverage generally requires a separate Part D plan.
Is Medicare Advantage an all-in-one plan?
Many Medicare Advantage plans combine Medicare Part A and Part B benefits with Part D prescription drug coverage. Some also include additional benefits, although coverage and costs vary by plan.
Can I keep Original Medicare and still get prescription coverage?
Yes. You can generally enroll in a stand-alone Part D plan alongside Original Medicare. You may also choose a Medigap policy to help cover certain out-of-pocket expenses.
Does Medigap cover prescription drugs?
No. Medigap policies do not cover most outpatient prescription medications. You will generally need separate Part D coverage for those medications.
Is Medicare Advantage less expensive than Original Medicare with Medigap?
Not necessarily. Medicare Advantage may have a lower additional monthly premium, while Original Medicare with Medigap typically involves multiple premiums. Your total costs depend on premiums, covered services, prescription medications, and healthcare use.
How can I compare Medicare plans in my area?
Visit Medicare.gov to compare available plans, review drug coverage, and evaluate plan costs. Check provider networks and plan documents directly before enrolling.
Explore Your Medicare Options With Life and Med
Understanding how hospital care, doctor visits, and prescription drugs fit together is an important step toward choosing Medicare coverage that meets your needs.
Whether you are considering a Medicare Advantage plan with prescription coverage or Original Medicare paired with Part D and optional Medigap, comparing your options can help you make a more informed decision.
Life and Med is here to help you navigate Medicare with greater confidence. Explore our Medicare Resource Center for more educational information about Medicare benefits, enrollment periods, coverage choices, and healthcare costs.
Visit Life and Med – Medicare Resource Center for local Medicare guidance.
📍 216 N. 3rd St., Suite B, Leesburg, FL 34748
📞 Call or text: 352-260-0202
Disclaimer: This article is for educational purposes only and does not constitute medical, legal, or insurance advice. Medicare coverage, costs, eligibility, and enrollment rules may change. Confirm current details with Medicare.gov and review plan-specific documents before enrolling.